
By Gareth Vaughan
As a long-term advocate of greater competition in New Zealand banking, it's fascinating to see the drums beating for a potential Commerce Commission market study.
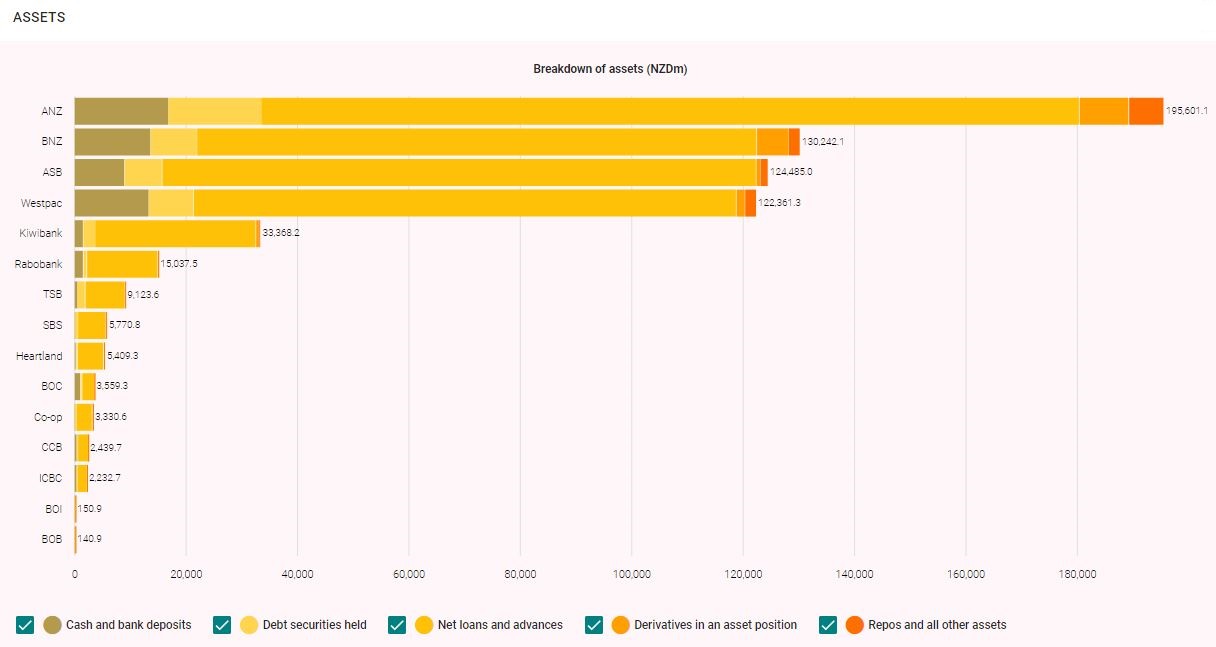
If you look at interest.co.nz's home loan tables you'll see there are 15 banks offering mortgages, plus a range of building societies, credit unions and other non-bank lenders. And on the deposit front you'll find deposit rates from 16 banks, plus the range of other financial institutions. So there are plenty of financial institutions operating in NZ. Yet year after year the same four big banks, ANZ, ASB, BNZ and Westpac, almost completely dominate the NZ banking market.
Contributing to this dominance are examples where successive governments, the Reserve Bank and Payments NZ, the bank owned payments overseer, have let down the New Zealand public and smaller NZ-owned banks and other financial institutions, effectively helping strengthen the dominance of the big four Australian owned banks.
This is certainly not to say this is the only factor. The sheer scale of the big four banks, operating primarily in a commoditised banking market dominated by largely homogeneous home lending and deposit collecting, gives them a big advantage. But there are clear examples, which I'll set out below, where the actions of our authorities have helped reinforce this dominance.
This has contributed to a NZ banking market described by Deutsche Bank banking analysts as a; "unique market structure, we are yet to find another one, generating oligopoly-like returns."
More sunlight needed on switching between banks
A key factor in a competitive market is how easy it is for customers to leave their current service provider and shift to another one. This is easy in NZ banking. However, I often come back to the thought that a lot of bank customers simply don't realise how easy it is to change banks.
A simple bank switching process, managed by the bank the customer is moving to, was established as long ago as 2010. Taking five business days, it was touted as the fastest in the world by Payments NZ, the organisation overseeing it.
In 2014 the Productivity Commission noted no public data was available on the number of customers moving between New Zealand banks even though banks are understood to get monthly data on the volume of customers switching between them. Such information, the Productivity Commission said; "would help demonstrate the effectiveness of the current switching process and give consumers greater confidence about the ease of switching banks - hence sharpening the overall level of competition between banks."
This data still isn't publicly available with a Payments NZ spokesman this week saying; "we don’t hold, or plan to hold, data on the number of customers who switch banks as this type of information is commercially sensitive."
Clearly it's not in the interests of the major banks, with big customer numbers, to necessarily promote the ease of changing banks. However, in the case of ambitious smaller banks you might think it would be. But I can't recall any recent campaigns by any banks promoting the ease of switching. So I asked some of the banks who might want to promote switching to see what they have to say. Kiwibank and TSB responded.
A Kiwibank spokeswoman noted it's easy, safe and fast to switch, and that there's information on Kiwibank's website for personal and business banking customers wanting to make the switch, with the bank's "customer-facing teams always here to help."
A TSB spokeswoman also said the switching process is easy.
"We haven’t promoted it since it was first introduced, but we have a new website launching soon, and this information will be part of this. At the moment we only have the step by step instructions on what to do when switching a home loan," said the TSB spokeswoman.
Here, clearly smaller banks could do more to promote the ease of moving your business to them, assuming they want it. And publicly available data, updated monthly or quarterly, on the volume of customers moving between banks, should be mandatory.
NZ a payments laggard
Payments is an area where NZ has been a slow mover. Notably shifting to processing electronic payments 365 days a year, introducing open banking, and merchant service fee regulation.
To give a bouquet alongside the brickbats, the current Government has moved to regulate merchant service fees, albeit more than 20 years after Australia did so and not to the extent I'd have liked. Nonetheless, this should directly reduce costs for small businesses that accept credit and debit card payments.
The move to 365 day a year payments, and work towards open banking, are both areas overseen by Payments NZ.
As Payments NZ notes on its website, it was formed in 2010 by the industry with support of the Reserve Bank. It governs NZ’s core payment systems and works with the industry to lead the future direction of payments in NZ. Payments NZ's shareholders/owners are ANZ, Westpac, BNZ, ASB, Kiwibank, TSB, HSBC and Citibank.
From May NZ banks are finally scheduled to begin 365 day a year payments, shifting from sending and settling payment transactions only between Monday and Friday. This won't, however, mean real-time payments where consumers, merchants, and financial institutions can pay friends and customers, settle bills, and transfer money immediately, 24/7. Alongside Israel, NZ is one of just two OECD countries without real-time payments.
Open banking requires banks to share product and customer data with customers and third parties, with the consent of the customer. The idea is that such data sharing should both increase price transparency, and enable comparison services to accurately assess how much a product would cost a consumer based on their behaviour. This could therefore enable the recommendation of the most appropriate products for individual customers.
Last November Labour's then-Commerce and Consumer Affairs David Clark announced a move towards open banking, saying this would ensure banks must share customer information if they request it, making it easier for New Zealanders to compare mortgage rates, apply for loans and switch banks. But Clark said actual implementation of open banking was still two years away.
Clark noted open banking is required of the Australian parents of NZ's big four banks, and "is a fixture" of the banking system in the United Kingdom being "a common place tool used overseas to increase competition and make it easier for customers to get better deals."
As long ago as 2017 National's Jacqui Dean, one of Clark's predecessors, was making noises about banks enabling open banking. Labour's Kris Faafoi, Dean's immediate successor, did the same. And in 2018 law firm Bell Gully weighed in saying; "strong, even urgent, political focus on open banking in other economies is currently absent in New Zealand."
With the bank owned Payments NZ in charge of the open banking standards and protocols, looking in from the outside it's easy to be cynical about slow movement in areas that could enable other financial service providers to increase competition with banks.
RBNZ tilts playing field in favour of big banks
An noticeable aspect of the Reserve Bank's Covid-19 response was how it tilted the playing field further in favour of NZ's big banks.
Major banks were at the centre of the Reserve Bank's large scale asset purchasing programme (LSAP), or quantitative easing. The QE saw the Reserve Bank buy about $53 billion worth of government and local government bonds from a range of banks including ANZ, BNZ, ASB's parent the Commonwealth Bank of Australia and Westpac.
Increasing the supply of money lowered interest rates further, providing liquidity to the banking system and encouraging banks to lend, which helped drive the explosion in bank mortgage lending and house prices in 2020-2021.
Additionally home lending banks were able to access $19 billion of three-year money priced at the Official Cash Rate through the Reserve Bank's Funding for Lending Programme (FLP). Eligible securities banks could pledge as collateral for FLP money included Residential Mortgage Backed Securities, New Zealand Government Securities, and Kauri debt issues.
Heartland Bank noted it didn't participate in the FLP because its home loan lending book wasn't big enough and the Reserve Bank had declined to include motor vehicle loans as collateral. Building societies and credit unions were excluded from the FLP, despite asking both to be included, and what they would need to do to be included. They were also excluded from the government-Reserve Bank arrangements enabling banks to offer mortgage repayment deferrals but offered them anyway.
Although they are small within the overall financial system, the likes of the Nelson Building Society and Wairarapa Building Society, plus the two biggest credit unions Credit Union Baywide and First Credit Union, are significant players in provincial parts of NZ.
On top of this the Reserve Bank twice delayed the starting date for the phasing in of new bank regulatory capital requirements to the frustration of NZ owned banks. In November 2020 TSB CEO Donna Cooper told interest.co.nz the delay meant NZ owned banks would remain disadvantaged against the Australian-owned ANZ, ASB, BNZ and Westpac from a capital perspective for even longer than expected.
"In residential [housing] lending, we’re required to hold on average 45% more capital than Australian-owned banks, for the same risk," Cooper noted.
Opportunity to tackle credit cards missed
Within the banking sector an obvious area the Government could've taken action on years ago is credit cards. In 2015 when Australian authorities, led by the Reserve Bank of Australia, were moving against high credit card interest rates, interest.co.nz sought to engage NZ authorities on the issue given credit card interest rates were at similar levels to Australia, even topping 20% in some cases.
At that time the Commerce Commission told us it could only act on credit cards if evidence emerged of collusion between banks to set rates at a certain level. The Reserve Bank told us its mandate was to regulate at a systemic level, to make sure the financial system remains sound, not from an individual customer protection perspective. And the then-National Commerce and Consumer Affairs Minister Paul Goldsmith told us it was for the banks themselves to explain the interest rates they charge.
In 2018 we even had then-Co-operative Bank CEO David Cunningham, a former Westpac executive, tell interest.co.nz credit cards were "a real area of customer harm," and ripe for a Commerce Commission market study. The deafening silence from NZ authorities continued.
The dominance of the oligopoly
We've known for years that NZ's major banks are right up there among the most profitable in the developed world across a range of measures. The oligopoly dominance of the big four, demonstrated in the Reserve Bank chart below, is a key factor in this.
The most recent Reserve Bank quarterly figures, from the December 2022 quarter, show the big four made combined net profit after tax of $1.646 billion. That's up $145 million, or 10%, year-on-year against the backdrop of a forecast recession. Meanwhile, the average net interest margin across the four rose to 2.4% in the December 2022 quarter from 2.025% in the December 2021 quarter, the average cost to income ratio fell to 35.7% from 37.6%, and the average return on equity was up 10 basis points to 14.1%.
NZ bank assets as of December 31, 2022
Winston's hot air
At times our politicians have failed to back up their rhetoric with action. Notably, going into the 2017 election NZ First's Winston Peters was pledging to "conduct a review of the foreign-owned banks focusing on competition." Peters told interest.co.nz a "bunch of subservient puppetized [NZ] politicians" weren't acting in the national interests of business and private citizens. However NZ First's coalition agreement with Labour didn't include any requirement for a banking inquiry.
Meanwhile, the Reserve Bank hasn't been keen on offering restricted banking registration to new entry digital, challenger banks, which has happened in the UK and Australia. Here the Reserve Bank instead points to the non-bank deposit taker option.
An idea I've floated before, that might help existing smaller banks and non-bank financial institutions better compete with the big banks, is sharing back office functions - potentially including a joint core banking system - as a way to reduce costs. Some discussions did take place on this between some NZ owned banks a few years ago. When I raised the issue with the Reserve Bank at the time I was told the regulator had heard nothing and thus wouldn't comment.
Threats to banks, real or imagined?
Speaking in an episode of interest.co.nz's Of Interest podcast, Reserve Bank Director of Money and Cash Ian Woolford suggested a central bank digital currency (CBDC) could boost competition and innovation in NZ's financial system by enabling more competition in transactions and payments offerings. The Reserve Bank is considering introducing a CBDC.
Th development of CBDCs has even led to questions about whether we still need banks. Credit rating agency Fitch is among those to have warned about the potential of disintermediation, or loss of business and relevance, for banks from the introduction of CBDCs.
"We believe the introduction of CBDCs will inevitably involve households and businesses converting some of their commercial bank deposits into CBDCs. All other things being equal, this would require banks to shrink their balance sheets - a process known as disintermediation," Fitch says.
A CBDC is the digital form of a country’s fiat currency, thus the NZ dollar in NZ's case. Woolford acknowledged technically members of the public could have an account directly with the central bank, thus disintermediating banks. However, this isn't on the Reserve Bank's agenda.
"I find it hard to see a world, and certainly the Reserve Bank would not want to have a world, where there were no financial institutions anymore and everything was run through the central bank. That is not what we are aiming to do," said Woolford.
Instead the Reserve Bank sees a CBDC more as a defensive move, to shore up the status quo and protect it and NZ's monetary sovereignty. Banks are front and centre of this status quo.
Big banks are also adept at delaying, embracing and partnering with emerging threats to their business. And they benefit from baked-in thinking in NZ that market solutions will always be the best ones. Hence the glacial moves towards open banking, merchant service fee regulation and failure to even contemplate that anything at all could or should be done about extortionate credit card interest rates.
If the Government does give the Commerce Commission the greenlight to undertake a market study into banking, probing the factors affecting competition, finding out how well competition is working and whether it could be improved, I'll keep a close eye on it. But I'll be surprised if it leads to any dramatic change.
*This article was first published in our email for paying subscribers. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.